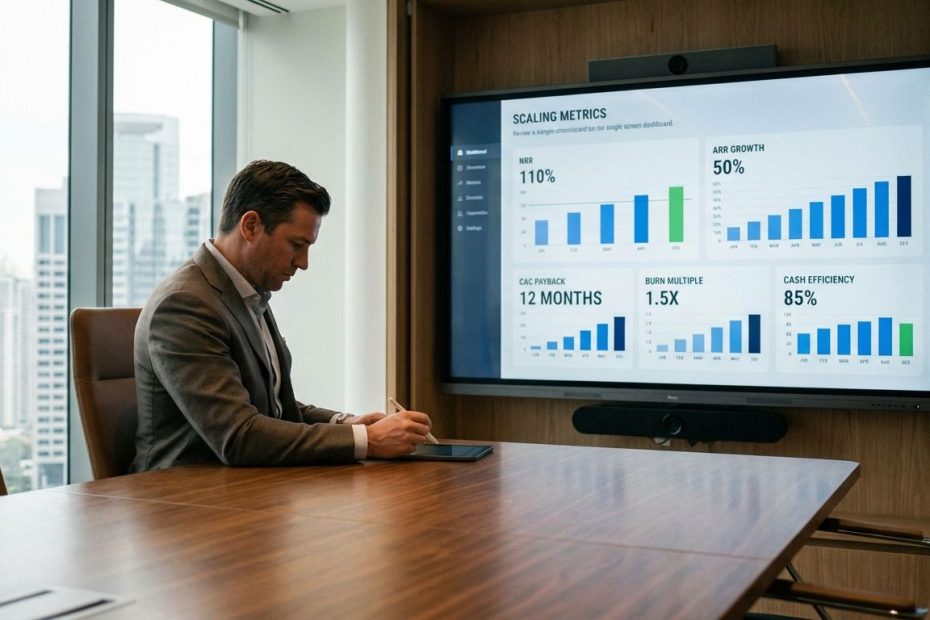
Scaling with precision comes down to running a tighter CEO dashboard: retention quality (NRR/NDR), growth durability (ARR growth), capital efficiency (burn multiple), and go-to-market efficiency (CAC payback, sales efficiency), all watched in a cadence that forces trade-offs early, not after the quarter closes.
This article gives you a CEO-grade set of metrics, how to interpret them without getting trapped by vanity numbers, and how to use them to make faster resourcing decisions. Expect concrete definitions, current benchmark anchors from public SaaS data, and practical “what to do when it moves” guidance you can apply in your next operating review.
What Are The Most Important “Scaling Metrics” A CEO Should Track Weekly (Not Just Quarterly)?
If the dashboard can’t fit on one screen and still drive decisions, it’s not a CEO dashboard. Weekly tracking should cover three constraints that determine whether you can scale safely: revenue quality, go-to-market productivity, and cash efficiency. The goal is not more measurement, it’s fewer metrics with sharper accountability.
Start with a “weeklies plus monthlies” structure. Weekly, monitor the leading indicators that move your quarter before finance catches up: gross retention trend by cohort, expansion signals (seat growth, usage growth, plan upgrades), pipeline creation, pipeline conversion, and cash burn rate. Monthly, lock the more stable unit economics and cash metrics: CAC payback, burn multiple, free cash flow trend, and customer concentration movement.
A useful CEO filter is: if a metric doesn’t change what you do with headcount, pricing, or product sequencing, it belongs one level down. McKinsey’s SaaS analysis points to a short list that correlates strongly with value: ARR growth, net retention, CAC payback, and free cash flow percentage. Those four cover the whole system, growth, retention-driven efficiency, GTM returns, and cash.
Weekly discipline also prevents the most common scaling failure: hitting growth targets by paying for it twice, once in discounts and once in churn later. A CEO dashboard that doesn’t show retention and payback together will let that happen quietly.
What Is Net Revenue Retention (NRR/NDR), And What Benchmarks Do CEOs Use In 2025?
NRR (often reported as NDR in public-company materials) answers a blunt question: does the customer base grow on its own after churn and downgrades, once expansion is counted. You measure revenue from a starting cohort, then include expansions, subtract contractions and churn, and express what remains as a percentage of the starting point.
The CEO reason to care is compounding. When NRR stays above 100%, the base funds growth, forecasting tightens, and sales has room to be selective. When NRR slips, every growth plan starts demanding more CAC, more discounting, and more headcount, which then stresses cash and forces reactive cuts.
Public SaaS data from Q2 2025 shows a median NDR of 108%, and it highlights that this level is materially lower than early 2022, when medians were over 120% in that dataset. That “108% median” matters for CEO benchmarking because it implies the market has normalized to lower expansion and/or higher churn than the post-2020 peak period.
McKinsey’s analysis also puts structure around “what good looks like.” In its sample, top-quartile SaaS companies showed median net retention around 130%, versus 104% in the bottom quartile. Use that gap as a warning: modest-looking declines in NRR are not cosmetic, they are often a signal that the operating model is shifting from compounding to replacement.
To run NRR like a CEO, never accept the blended number alone. Require a decomposition every month: logo churn, gross revenue retention, contraction, expansion by motion (upsell, cross-sell, usage), and renewal outcomes by segment. That decomposition is where the levers live, and it keeps accountability clean across Product, Customer Success, and Sales.
What Is The Rule Of 40, And Is It Still Relevant For CEOs In 2026?
The Rule of 40 is a board-level control metric: growth rate + profit margin should be at least 40%. In SaaS, the “profit margin” is frequently expressed as free cash flow margin, because cash quality matters when capital becomes selective and when scaling spend pulls forward costs.
This metric still earns a place in CEO reviews because it forces trade-offs into daylight. If growth slows, you either improve margin or accept that valuation and financing terms will usually tighten. If growth accelerates but margin collapses, the same tension shows up, just from the other direction.
McKinsey’s work ties Rule of 40 performance to value outcomes and points out that ARR growth is a better growth input than reported revenue for many SaaS companies because revenue recognition can lag booking reality. It also notes that for larger SaaS companies, free cash flow percentage is a key component industry watchers use when evaluating Rule of 40 performance.
For CEO use, treat the Rule of 40 as a governance metric, not a weekly steering wheel. Use it to set boundaries for annual planning and to pressure-test whether the operating model can fund the next phase. Pair it with the metrics that explain why the Rule of 40 is moving: net retention, CAC payback, and burn multiple.
Also, don’t let the Rule of 40 become a single-number hiding place. If the company hits 40 by cutting growth investments that protect retention, the score can look good right up until churn shows up later. The rule is useful when it drives the right behavior, not when it becomes a slogan.
What Is Burn Multiple, And What Burn Multiple Is Considered Good?
Burn multiple is a capital efficiency metric that tells you how many dollars of net burn it takes to produce one dollar of net new ARR. The formula is straightforward: Burn Multiple = Net Burn / Net New ARR. It’s one of the cleanest CEO metrics because it connects cash consumption directly to durable subscription growth.
As a CEO, burn multiple prevents a common self-deception: celebrating ARR adds while ignoring that the company is buying them at an accelerating cost. When burn multiple worsens, it usually means one of three things is happening: acquisition is getting more expensive, net retention is weakening (so net new ARR shrinks), or both. The metric doesn’t tell you which, it forces you to find out fast.
MetricHQ defines burn multiple as a measure of how many dollars a startup burns to generate each dollar of net new ARR, with higher meaning less efficient growth. That definition is enough to make it operational: you can move it by improving sales productivity, tightening discounting, lifting retention, reducing cycle time, or reallocating spend to segments with better payback.
In operating reviews, require burn multiple by segment if data quality allows it. A blended burn multiple can hide that mid-market is efficient while enterprise is dragging, or that a new product line is absorbing spend without producing durable ARR. Capital efficiency becomes real when you can point to where the burn is buying repeatable growth.
How Do CEOs Measure Go-To-Market Efficiency: CAC Payback Vs. “Magic Number”?
CAC payback answers a cash question: how long it takes to recover customer acquisition cost from gross profit. Magic Number answers a productivity question: how effectively sales and marketing spend turns into recurring revenue growth. Most teams need both, and the CEO needs them presented in a way that prevents fighting over definitions.
CAC payback is the metric that protects runway. If payback stretches, the company either raises prices, improves gross margin, fixes retention, reduces acquisition cost, or slows hiring, usually a combination. McKinsey reports a wide performance gap in payback period between top- and bottom-quartile SaaS companies, citing medians of 16 months versus 47 months in its sample. That spread is a reminder that payback is not a finance-only metric; it is an operating model test.
Magic Number is commonly calculated as annualized incremental ARR divided by prior-period sales and marketing spend, and it’s often used to compare GTM efficiency across periods. Many CEOs like it because it moves faster than payback, yet it can be distorted by timing, ramp, and changes in ARR definition. That’s why you treat it as directional, then validate with payback and cohort outcomes.
A practical CEO rule: when Magic Number drops, don’t accept “pipeline is fine” as an answer. Demand the chain: pipeline creation → conversion → discount rate → ramp time → retention of new cohorts. If any link weakens, the business is paying more for lower-quality ARR, and that will show up in burn multiple and NRR with a lag.
Tie GTM efficiency to segmentation. If the company sells into multiple customer sizes or multiple industries, a single CAC payback hides real behavior. Build payback by segment, attach an accountable owner, then set investment guardrails that prevent cross-subsidizing a weak segment with a strong one.
What “People And Execution” Metrics Predict Scaling Success Before The Financials Show It?
Execution metrics matter because financials are slow. Revenue can stay stable for quarters while product adoption is slipping, renewal risk is rising, and account expansion has stopped. CEOs who wait for the income statement to speak usually discover the issue when options are already constrained.
Focus on metrics that predict retention and expansion. Track time-to-value for new customers, activation rates by cohort, and sustained usage or adoption measures tied to renewals. If those signals weaken, treat it as a churn problem in progress, not as a product analytics curiosity.
NRR decomposition is the bridge between “execution” and “finance.” When gross retention dips, inspect onboarding, product reliability, support responsiveness, and customer success coverage. When expansion slows, inspect pricing, packaging, product depth in key workflows, and sales motions that drive add-ons. Keep this decomposition visible in leadership meetings so that churn and expansion never become after-the-fact explanations.
Also track capacity metrics that show whether the organization can execute without creating hidden debt. Monitor pipeline per rep, quota attainment distribution, ramp time, support tickets per customer, and customer success coverage ratios. These measures are not vanity when they predict service quality, renewal outcomes, and sales efficiency.
Finally, require a narrative that connects people investments to metric outcomes. Headcount plans should not be “more AEs equals more ARR.” They should specify expected pipeline creation, conversion, retention impact, and payback impact. That’s what scaling with precision looks like in practice.
What Should A CEO Do When Retention Is The #1 Growth Lever, Yet The Org Treats It Like A Support Function?
Retention becomes the number-one lever when new acquisition gets expensive and when expansion drives a material share of growth. Treating retention as “post-sale cleanup” guarantees that product decisions, sales promises, and customer success capacity will drift apart. Once that happens, the company pays in churn, margin pressure, and noisy forecasting.
Start by making retention a first-class operating number with weekly visibility. Put gross retention, expansion, and renewal pipeline in the same review as new bookings. If sales celebrates bookings without owning churn risk created by discounting or mismatched customers, retention will always lag and the business will keep buying growth twice.
Fix ownership with clean lines. Product owns adoption and value delivery in the workflow, Customer Success owns renewal execution and health management, Sales owns expansion motion and account strategy, Finance owns pricing discipline and discount governance. The CEO owns the alignment and enforces that a quarter doesn’t “count” if the ARR is low quality.
Then build the operating system that makes retention movable. Require cohort reporting that shows what happens to customers six and twelve months after acquisition, by segment and by acquisition channel. Tie compensation and promotion decisions to retention outcomes, not just bookings. When the company starts paying for retention, the organization starts treating it like growth.
Public SaaS NDR medians near 108% in Q2 2025 show a market where expansion is no longer effortlessly high for most companies. That means disciplined retention and expansion execution is a separator again. CEOs who operationalize retention as a growth engine will out-forecast and out-invest peers who still treat it as a service function.
What Are The Key SaaS Scaling Metrics A CEO Should Watch?
- NRR/NDR, ARR growth, CAC payback, burn multiple, FCF margin
- Track weekly trends, review monthly unit economics, enforce segment-level accountability
Run Your Metrics Like A Capital Allocator, Not A Reporter
Precision scaling means allocating resources to the highest-return growth loops: retention-driven expansion, efficient acquisition, and cash conversion. Keep your CEO dashboard tight, insist on decomposition that shows drivers, and tie execution owners to each movement. Use NRR to judge revenue quality, burn multiple to judge capital efficiency, and CAC payback to protect runway. Use Rule of 40 as a governance boundary, then run the business on the levers that move it. The companies that win the next phase won’t measure more, they’ll decide faster off fewer numbers.
If sharper CEO dashboards, retention playbooks, and efficiency benchmarks are useful, follow more writing on my substack.

Jay Holstine is a Vistage Chair and veteran tech CEO with 20+ years of experience in SaaS and operations. The founder of SigmaFlow and former CEO of Freightflow, he now leads a Dallas–Fort Worth CEO peer group and advises executives on strategy, process improvement, and scalable growth.